Refinancing Into Higher Rates: Building the Operating Story Lenders Underwrite
$18.7 billion of hotel CMBS debt matures this year, most of it written when money was cheap. The replacement loan gets sized on trailing NOI that a lender believes. A reporting stack that produces a clean, system-generated data room every month (normalized NOI with evidence, comp-set benchmarking, a forecast track record and a rolling 13-week cash model) is how an owner moves that belief, and the proceeds with it.
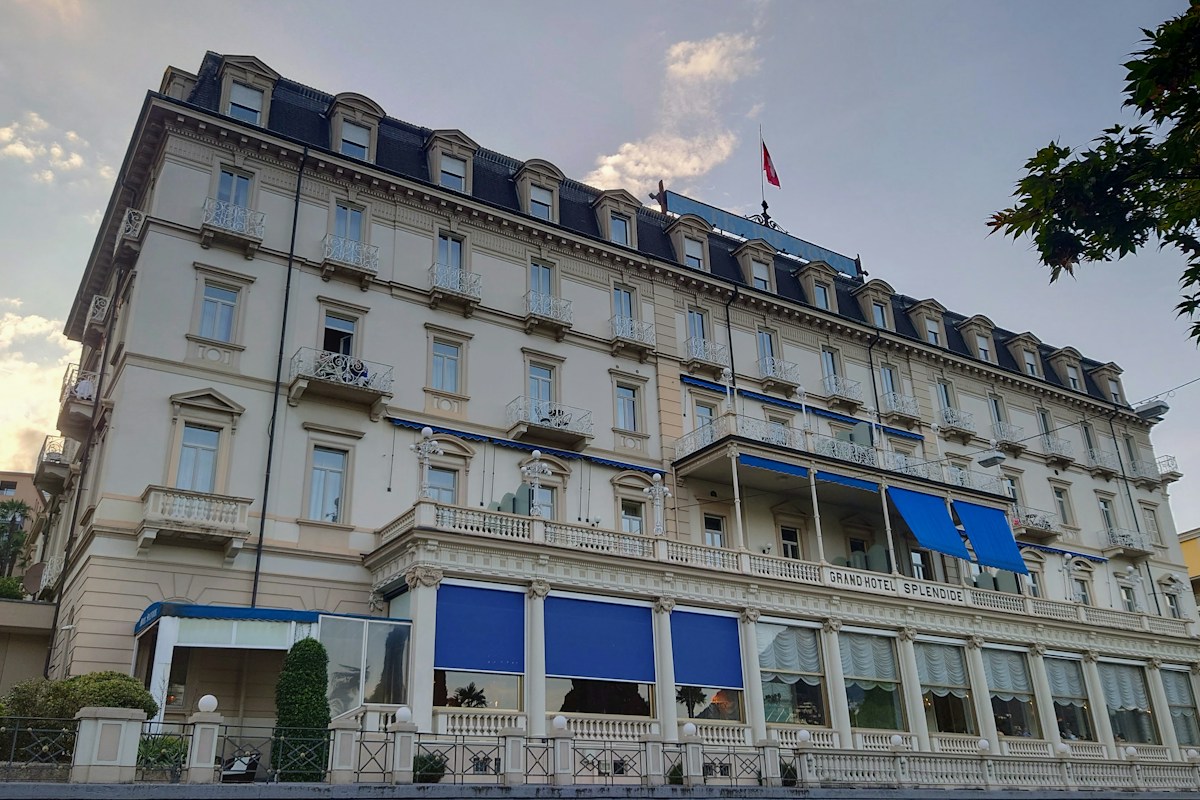
Look at the building in the photo above. A lakeside grand hotel, blue awnings out, flag on the roof, a hundred-odd windows under a slate mansard. A guest sees the view. A buyer sees the rooms. A lender sees a trailing twelve months of cash flow and a roof that will need money someday, and it prices the loan on which of those it can prove.
That's the refinancing problem in one picture.
I owned ten hotels. I also founded Collective Retreats, grew it to ten locations and saw it acquired in 2025, and nothing teaches you about your own reporting like strangers reading it harder than you ever did. Whichever seat I was in, the lesson was the same. The hotel doesn't get financed. The file does.
This year a lot of files are going back to market at once, and they're going back into a rate world that didn't exist when the loans were written. What follows is about the one part of that an owner controls: the operating data package the lender underwrites, and the reporting stack that builds it every month instead of in a panic six weeks before maturity.
The Problem: Same Hotel, Different Loan
Trepp counts 596 hotel-backed CMBS loans with a combined $18.7 billion maturing in 2026. Nearly 70 percent of that balance is floating-rate debt. The FBT Gibbons team that published the count put the gap plainly: a loan written in 2016 or 2021 may carry 4 to 6 percent with a debt yield of 10 to 13 percent, and a new loan this year comes in around 6 to 7 percent.
Coupons are only half of it. The lender that writes the new loan also sets amortization, which most of the old interest-only CMBS paper didn't have. Access Point Financial, a hotel lender, says debt service on refinanced loans often runs about 40 percent higher than under the original terms.
So the sizing question changes. It used to be "what's the hotel worth." Now it's "how much loan does this NOI carry at today's coverage." HVS puts current requirements at a DSCR of 1.30x to 1.50x and loan-to-value of 55 to 65 percent for stabilized hotels, and says lenders "will underwrite the trailing 12 to 24 months of actual operating results, not projections or pro formas."
Read that last part twice. The number that sizes your loan is already written. It's in the last year of your P&L. The only open question is how much of it the lender accepts.
Here's what that looks like on an illustrative hotel. Same building, same NOI, two loans.
| Scenario | NOI the lender accepts | Annual debt service | DSCR | Proceeds gap vs $30M payoff |
|---|---|---|---|---|
| Existing loan at 4.5% interest-only | $3.30M | $1.35M | 2.44x | None |
| Same $30M at 7.0%, amortizing | $3.30M | $2.54M | 1.30x | Below a 1.40x test |
| New loan sized to 1.40x, NOI accepted as reported | $3.30M | $2.36M | 1.40x | $2.2M short |
| Lender haircuts unsupported add-backs by 5% | $3.14M | $2.24M | 1.40x | $3.6M short |
| Owner proves one-time costs, NOI accepted 5% higher | $3.47M | $2.47M | 1.40x | $0.8M short |
At those terms, every $100,000 of NOI the lender believes is worth about $840,000 of proceeds. That's the whole case for this article. The spread between the bottom two rows, about $2.8 million, isn't rate and it isn't the market. It's documentation.
The Data: Where the Pressure Sits
The lodging book isn't in crisis. Trepp's October update had the lodging CMBS delinquency rate down 24 basis points to 5.94 percent, and CRED iQ found hotels face the smallest refinancing rate gap of any property type, about 32 basis points, because many hotel loans already priced close to today's market. Averages hide the hotels that will struggle, though.
Limited service is where it shows. Trepp's lodging analysis found a 10.34 percent nonperforming rate in limited-service CMBS loans, and 19.9 percent of that balance below an 8 percent debt yield, the line Trepp uses as a common refinancing threshold. The median coverage in that segment fell from 1.81x at underwriting to 1.37x, with net cash flow 9.7 percent below underwriting.
Costs are the reason. AHLA's 2026 State of the Industry report put wages and benefits at nearly $128 billion in 2025 and projected nearly $131 billion for 2026, while PwC's May outlook called for RevPAR growth of 2.9 percent. Revenue that rises slower than labor doesn't reach NOI, and NOI is all the lender reads.
| Measure | Figure | Source | What it means for a borrower |
|---|---|---|---|
| Hotel CMBS maturing in 2026 | $18.7B, 596 loans | Trepp | A crowded lender queue; clean files get read first |
| Share of that balance on floating rates | Nearly 70% | Trepp | Many borrowers already pay today's rates; the shock is amortization and coverage |
| Lodging CMBS delinquency, Oct 2026 | 5.94% | Trepp | The sector is stable; individual weak assets are not |
| Limited-service balance below 8% debt yield | 19.9% | Trepp | Expect paydowns or fresh equity at maturity |
| Limited-service median DSCR, underwriting to now | 1.81x to 1.37x | Trepp via Hospitality Investor | Below the 1.40x many lenders test at |
| Typical DSCR requirement | 1.30x to 1.50x | HVS | The math in the first table |
| Debt service change on refinance | About +40% | Access Point Financial | NOI has to carry far more than it did |
One more data point, and it's a softer one. Writing in Hotel Executive, Jacqueline Villamil and David Kasten of Strategic Solution Partners said lenders now have more applications on their desks than they can handle, and that "the first thing lenders evaluate is not just the numbers; it is whether those numbers make sense in context." A credit officer with a full desk reads the package that answers its own questions.
The Framework: What a Lender Actually Underwrites
Strip the term sheet down and a hotel lender is testing four things.
Is the trailing NOI real? That means the T-12 ties to the general ledger, the general ledger ties to bank deposits, and every add-back has a document behind it. HVS's advice to owners is to keep normalized NOI clean and well-documented, separating recurring costs from one-time items.
Is it holding up against the market? The STR or comp-set report says whether the hotel is gaining or losing share. A lender reads a falling index as falling NOI that hasn't shown up yet.
Does management know its own hotel? This is the forecast question, and owners underrate it. Lenders size on actuals, but they still ask for a budget and a three-to-five-year pro forma. A team that can show its past forecasts landed close gets its pro forma read as a plan. A team that can't gets it read as a sales document.
Can the hotel survive a bad quarter? Cash, reserves, the PIP schedule, seasonality, the franchise term. A rolling 13-week cash model answers most of it in one page.
Here's each request, and the system that should be producing it without anyone opening a spreadsheet.
| What the lender asks for | Why they ask | System that produces it | How it's usually built today |
|---|---|---|---|
| T-12 and 24 months of monthly P&Ls, USALI format | Sizes the loan | Accounting GL, mapped to USALI, tied to bank and PMS | Controller exports and reformats at month-end |
| Normalized NOI with add-back support | Decides how much NOI is accepted | GL plus an add-back register linked to invoices and approvals | A tab of adjustments with no backup |
| STR or comp-set reports with commentary | Market share trend | Automated benchmarking feed plus drafted analysis | Raw PDFs attached without explanation |
| Budget, pro forma and forecast history | Credibility of management | Forecast archive with accuracy scoring | Current budget only; old versions lost |
| Rolling cash forecast | Downside resilience | 13-week model fed from PMS on-the-books, AP and payroll | Built once for the lender, never updated |
| Franchise agreement, PIP status, capex log | Brand and capital risk | Document store with term and PIP tracker | Emailed on request, sometimes the wrong version |
The Mechanism: A Monthly, System-Generated Data Room
The fix is to stop treating the lender package as a project. Build it as a by-product of the monthly reporting the hotel already does, so on any given day the data room is at most a month stale. Five pieces.
1. One store, tied out. Connectors pull the PMS, POS, payroll, accounting GL and bank feeds into a single database keyed by date and USALI account. Reconciliation runs automatically: PMS room revenue against the GL, GL cash against bank deposits, payroll against labor lines. Any break above tolerance stops the monthly package until the controller clears it. This is the same backbone as the owner reporting pipeline in yesterday's piece, pointed at a different reader.
2. A normalized NOI engine with an evidence trail. This is where the money is. A classifier reads every GL line and every invoice above a threshold and flags candidates for normalization: the storm repair, the one-off legal bill, the pre-opening cost of a new outlet, the equipment replacement that should arguably have been capitalized. It doesn't decide anything. It builds a register, attaches the invoice, the approval and a one-line rationale to each item, and the controller accepts or rejects. When the lender asks why NOI was adjusted, the answer is a link, not a phone call. A haircut on unsupported add-backs is what costs the owner in the fourth row of the first table, and this register is what avoids it.
3. Automated benchmarking with written analysis. The STR or comp-set feed lands monthly. The system computes occupancy, ADR and RevPAR index by segment and by month, then a language model drafts two or three paragraphs explaining the movement from data already in the store: a group that washed, a new competitor, a renovation that took rooms out of service. Each sentence links to the figures behind it, the model says so when it can't find a driver, and a person approves before it goes into the room. Raw STR PDFs with no analysis are one of the things that slow lenders down; this takes the question off their desk.
4. A forecast archive and accuracy score. Every forecast and budget version gets saved with its date. Each month the system scores the 30-, 60- and 90-day forecasts against what happened (the method is in our forecast accuracy benchmarking piece). After twelve months the hotel has something most borrowers don't: evidence of how good its own predictions are.
5. A rolling 13-week cash model and a refinance simulator. On-the-books revenue from the PMS, scheduled AP, payroll runs, debt service and reserve deposits roll into a weekly cash view that refreshes every Monday. Beside it sits a simple sizing model: given trailing NOI, today's quoted rate, amortization and the lender's DSCR and debt yield tests, how much loan does the hotel carry and how big is the gap to payoff. Run it monthly from eighteen months out. If the gap is growing, the owner knows while there's still time to do something about NOI.
The data room itself is just a folder structure the system fills, with versioning and a Q&A log. Lender questions go into the log, an assistant drafts answers from the store, the controller or owner approves, and any question asked twice becomes a standing page in the room.
| Data room item | Source system | Refresh | Who signs off |
|---|---|---|---|
| Monthly P&L, T-12 and prior two years, USALI | Accounting GL | Monthly after close | Controller |
| Normalized NOI bridge and add-back register with invoices | GL plus document store | Monthly | Controller, then owner |
| Comp-set index trend with written analysis | Benchmarking feed plus drafter | Monthly | GM or revenue manager |
| Budget, pro forma and forecast accuracy history | Forecast archive | Monthly | Revenue manager |
| Booking pace and group pipeline | PMS, sales system | Weekly | Director of sales |
| 13-week cash forecast and refinance sizing | PMS, AP, payroll, debt schedule | Weekly | Controller |
| Franchise agreement, PIP schedule, capex log, property condition notes | Document store and capex tracker | On change | Owner or asset manager |
| Lender Q&A log | Q&A assistant | As asked | Owner |
Forecast Accuracy as a Credit Signal
I want to spend a minute on the forecast archive, because it's the piece owners skip and the one that changes the conversation most.
A lender reading a pro forma is asking one question: do these people know what's coming? Usually there's no way to answer it, so the lender haircuts the projections and moves on. A hotel that can hand over two years of dated forecasts next to actuals removes the guess.
At Starwood I worked across more than 800 hotels as VP of sales strategy and operations, and the properties that got the benefit of the doubt in any review were the ones whose numbers had been right before. Credit works the same way.
| 30-day rooms revenue forecast error (12-month average) | Bias | How a lender is likely to read it | What to put in the room |
|---|---|---|---|
| Under 3% | Balanced | Management knows the hotel; the pro forma is a plan | Full accuracy history, front and center |
| 3% to 6% | Balanced | Credible, normal for a resort or group-heavy hotel | History with notes on the misses and why |
| 3% to 6% | Consistently high | Optimistic team; expect a haircut on projections | History plus the correction already made |
| Over 6% | Any | Projections discounted heavily | Fix the forecast process before going to market |
| No history kept | Unknown | Default haircut | Start archiving now; a year of data helps the next refinance |
Bias matters more than the headline error. A forecast that misses high every month tells the lender the budget is high too.
Implementation: Eighteen Months Out, Not Six Weeks
The timing is the whole game. Lenders read 12 to 24 months of actuals, so the NOI work and the documentation have to start before the window the lender will look at. Six weeks before maturity is too late to change anything but the formatting.
Eighteen months out, stand up the store and the reconciliation. Map the GL to USALI if it isn't already, connect the PMS, payroll and bank feeds, and run the tie-outs until they come back clean three months straight. Start the forecast archive the same week. It costs nothing and every month of history counts.
Fifteen months out, turn on the add-back register and go back through the trailing year. Most hotels find costs that were one-time and never labeled, and some that were expensed when the accounting standard allowed capitalizing them. HVS makes the point that major equipment replacements and damage repairs should be capitalized where standard accounting allows. Do that with your accountant, document it, and do it now, not in the package.
Twelve months out, the monthly data room should be assembling itself. Turn on the benchmarking drafter and the 13-week cash model, and start running the refinance simulator against current quotes. If the proceeds gap is bigger than the equity you're prepared to put in, that's a year to work on NOI, talk to the franchisor about the term, or line up mezzanine (HVS puts it at 12 to 14 percent) before you need it.
Six months out, the package goes to a broker or lenders as a link to a live, versioned room, not a zip file. Questions go into the log. Answers come from the store.
| Months before maturity | Build | Done when | Measure |
|---|---|---|---|
| 18 | Data store, USALI mapping, reconciliation, forecast archive | Three clean monthly tie-outs | Breaks per month; days to close |
| 15 | Add-back register; review of trailing year | Every adjustment has a document and an approver | Documented vs undocumented add-backs |
| 12 | Benchmarking drafter, 13-week cash model, refinance simulator | Data room assembles monthly without manual work | Proceeds gap at current quotes |
| 9 | NOI and capital actions from the simulator | Gap plan approved by owner | Trailing NOI trend |
| 6 | Live data room and Q&A log to lenders | Term sheets received | Days from request to answer |
If you want to know which of your systems can feed a monthly data room today and which will need a workaround, that's the first thing our AI and technology scorecard and reporting engagement maps.
None of this changes the rate. It changes what the rate gets applied to, and at 1.40x and 7 percent, a hundred thousand dollars of NOI a lender believes is worth most of a million dollars of loan.
Frequently Asked Questions
What do lenders look at when refinancing a hotel loan?
Trailing 12 to 24 months of actual operating results, normalized NOI, debt service coverage (HVS puts current requirements at 1.30x to 1.50x), loan-to-value (55 to 65 percent for stabilized assets), comp-set performance, the franchise agreement term, PIP and capital needs, and the sponsor's track record. Lenders size on actuals, not pro formas, though they still ask for a budget and multi-year projection.
How much hotel CMBS debt matures in 2026?
Trepp counts 596 hotel-backed CMBS loans totaling $18.7 billion maturing in 2026, with nearly 70 percent of that balance on floating rates. Loans written in 2016 or 2021 often carried 4 to 6 percent coupons; replacement loans this year are generally quoted around 6 to 7 percent, usually with amortization.
What is normalized NOI and why does documentation matter?
Normalized NOI is trailing NOI adjusted for one-time items such as a storm repair, a legal settlement or pre-opening costs. Lenders accept add-backs they can verify and discount the rest. A register that links each adjustment to the invoice and approval keeps the accepted NOI, and the loan proceeds sized on it, as high as the facts allow.
Does forecast accuracy affect hotel loan terms?
Indirectly. Loans are sized on trailing actuals, but lenders still read the budget and pro forma to judge risk, structure and extension terms. A dated archive of past forecasts against actuals shows whether management's projections have been reliable, which changes how heavily a lender discounts them.
When should a hotel owner start preparing for a refinance?
About eighteen months before maturity. Lenders read the trailing 12 to 24 months, so data cleanup, add-back documentation and any capitalization decisions need to land inside that window. Starting six weeks out leaves time only to format what already exists.
If a maturity is on your calendar and the data room doesn't exist yet, AI for Hoteliers is where GMs and controllers learn to build this reporting with AI they already control, with templates and weekly office hours to get the add-back register and forecast archive running. I owned ten hotels, so I'd start where a lender would, with the T-12. If that sounds useful, book a free 15-minute call.
Peter Mack is a hospitality technology strategist and founder of HospitalityOS, helping independent hotels and resorts implement AI systems that drive revenue and reduce operational costs. With 25 years in hospitality operations and technology, he has worked with properties of all types and in every region as both a General Manager, Founder, Operator, Asset Manager, and Owner.